Author:Used Wholesale Manufacturer TIME:2026-08-13
Shoe supplier staged-payment scorecard
Afterpay style terms in a wholesale shoe offer should be treated as staged payment language, not assumed consumer finance protection. The buyer needs to compare the cash price and total staged price, verify the responsible supplier and beneficiary, tie each payment to observable stock or document milestones, and define what happens when evidence fails. The scorecard below evaluates process quality rather than rewarding a long installment schedule. Legal rights, fees, title, refunds and cross-border enforceability depend on the actual contract, payment provider and jurisdiction and need qualified review.
Reconcile legal supplier name, business address, accountable contact, contracting entity, invoice issuer and payment beneficiary through suitable evidence. Repeat the beneficiary check before each payment rather than relying on the first transfer.
Score down unexplained party changes, unrelated accounts, informal invoice substitution and pressure to pay before records are complete. A familiar payment label or platform logo does not establish who is responsible for the shoe order.
verified responsible entity
same approved identity
reconciled for every transfer
independent confirmation
List cash goods price, staged goods price, deposit, installments, finance or service fees, currency conversion, bank charges, late or rescheduling costs where applicable, and delivery endpoint. State which amounts are fixed and which can change.
A lower initial deposit can accompany a higher total cost or earlier risk transfer. Do not compare a port-level cash quote with a warehouse-level staged quote. Use the same goods scope, quantity, currency date and route boundary.
same goods and endpoint
all scheduled amounts
provider bank and currency
identified change conditions
Before deposit, close supplier identity, written grade, quantity basis, current-stock evidence, allocation or sampling rule, commercial terms and the refund or remedy process. Record what the deposit reserves and the deadline for the next milestone.
A deposit should not be scored as safe merely because it is small. If the stock relation is unclear or the payment party conflicts, the milestone remains open. Qualified legal and payment advice may be needed before funds move.
responsible party closed
offer-linked evidence
grade quantity and allocation
written failure route
Weight scores for the buyer's risk, but keep any unresolved P0 identity or stock conflict as a stop regardless of the total.
| Score field | Evidence | Strong control | Automatic concern |
|---|---|---|---|
| Identity | Contract, invoice and beneficiary | Names reconcile at every payment | Unexplained party change |
| Total price | Cash and staged cost sheet | Same scope, currency and endpoint | Hidden or variable fee |
| Deposit | Current stock and written scope | Reservation and remedy clear | No offer-linked stock |
| Inspection | Selection, fields and tolerance | Buyer-controlled reproducible test | Showcase treated as random |
| Balance | Packing, loading and documents | Final versions reconcile | Payment before material closure |
| Delivery | Package-linked receiving results | Variance and remedy closed | Terms used to excuse weak stock |
The supplier score is meaningful only when a critical identity or evidence failure cannot be averaged away by convenient payment timing.
Specify who selects the sample, package positions, pair count, grade fields, allowed variance, evidence format and deadline. Compare product claims and physical grade separately. Keep failed or unresolved fields visible in the report.
A supplier-selected showcase does not equal a random inspection. If the method changes, record the reason and approval. The next payment should follow only under the contract's observable acceptance condition, not a general message that production is complete.
buyer supplier or independent role
random stratified or exact lot
claim and physical status
measured response rule
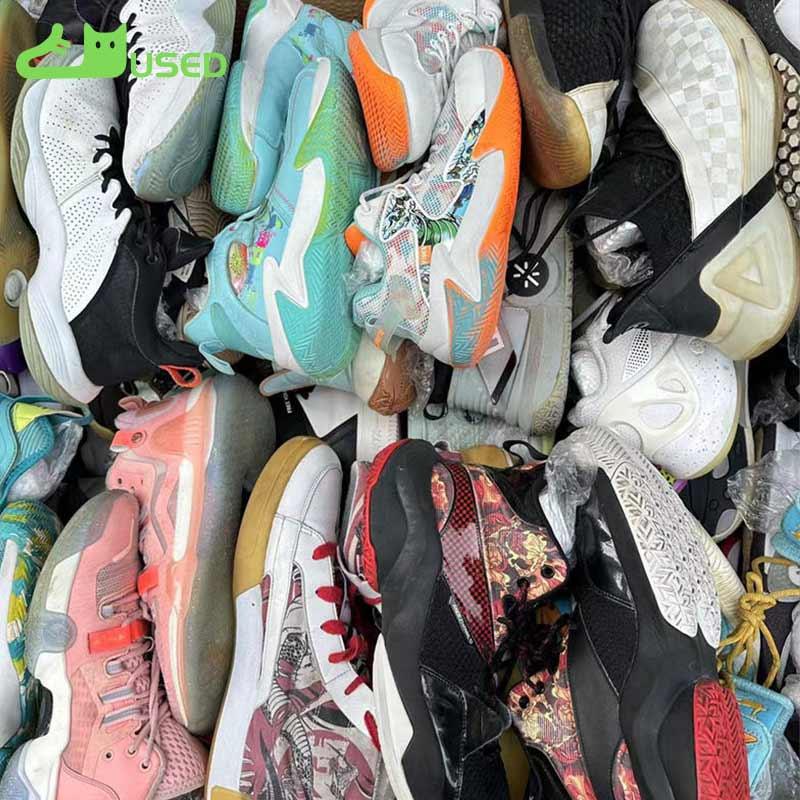
Before balance, reconcile approved quantity, package marks, packing list, weights, current stock status, loading evidence and applicable transport or route documents. Confirm the final invoice and payment beneficiary again.
A closed package is not enough if contents or documents remain inconsistent. Score the supplier on version control, response time and whether exceptions have accountable owners. Hold, amend or proceed only through the approved contract and professional process.
marks counts and weights
approved stock and sequence
reconciled final versions
confirmed amount and beneficiary
Plot each payment date against evidence received, inventory control, shipping milestone, expected arrival and first realistic resale date. Include funds held in service-pending or evidence-hold stock after arrival.
Longer terms do not automatically improve cash flow if the buyer pays most of the order before inspection or receives low released yield. Stress test delay, lower yield, added fees and slower resale. Set a maximum exposure the business can carry without relying on optimistic sales.
date and amount
what evidence or stock right exists
route and delay scenario
credit remedy or exit option
At receiving, compare package marks, counts, category mix, grade, substitutions, damage, wetness and documents with the milestone evidence. Preserve exceptions before service and record whether the supplier responds inside the agreed process.
Update scores for identity consistency, evidence quality, inspection variance, document control, communication and remedy completion. Do not let flexible terms compensate for poor stock. Change one milestone, tolerance or exposure ceiling for the next order.
approved versus received
owner and timing
credit replacement or disposition
one next-order control
No. Rights and remedies depend on the actual contract, provider and jurisdiction.
Use the complete staged total, fees, currency costs and the same delivery boundary.
No. Verify responsibility, scope and current-stock relation first.
A defined selector, sample, fields, tolerance and response process.
Not when delivered stock, documents or remedies remain poor.
Staged payment helps only when each release point closes a real evidence field. The used mixed shoes wholesale category provides the mixed-footwear context; verified identities, total-cost comparison, controlled inspection, reconciled documents and delivery scoring govern the terms. Use the page inquiry form to request the stock scope, milestone evidence, packing basis and proposed payment schedule.
Direct Factory Supplier of Used Shoes For African Markets In China
 Tel: +8618606960861
 Email: info@usedshoeswholesale.com
 MP/WhatsApp: +8618606960861
 Manufacturer Address:Cizao Town, Jinjiang City, Quanzhou City, Fujian Province